SIGforum
Financial Question
October 08, 2026, 04:38 PM
trapper189Financial Question
quote:
Much as I hate paying interest on a loan, it's apparent that paying extra on the principle as often as I can (which I've been doing) is a better plan.
If you are paying ordinary income tax rates on the money you are using to pay down the loan, then it doesn’t matter if you use IRA money to do so as long as you don’t push yourself into the next tax bracket.
October 08, 2026, 04:43 PM
GeorgeairAt the risk of making you an older fart than you already are, aren't you in age range where you must take RMDs anyway? Not that this will pay off the truck, but from your post it sounds like you may not be doing so from that IRA?
You only have integrity once. - imprezaguy02
October 08, 2026, 04:48 PM
trapper189From his first post, he’s 75, so yes he is subject to RMD. I missed it as well, I thought he was only 73.
October 08, 2026, 04:54 PM
sourdough44It is good to have some liquid $$ for emergencies, so there’s that. I don’t think it’s worth refinancing for a 1% gain, lower, if even able.
With the end of the year coming up you could easily split it up to control any taxable amounts in 2026, then start on 2027.
I’m already lightly planning 2028, a year with an expected low W-2 to liquidate a 529 account.
October 08, 2026, 04:59 PM
Fly-SigOne option would be to withdraw from the IRA each year just up to the level where it would trigger higher taxes if you took more. e.g. if you are in the 10% tax bracket, you could withdraw a bit so that you are just $1 under the next higher bracket (12%).
Unfortunately, in retirement there are numerous thresholds at play which make it a complicated and tedious process to figure out how much more tax you pay for another $1 withdrawal from your IRA.
I expect that taking out the entire $20k will trigger some taxes bigger than you might think.
Another option is to sell some investments in a regular brokerage account that have
long-term gains. If your other income is below $98,900 then your
long-term capital gains are taxed at 0%. That's for married filing joint. Keep in mind that those long-term capital gains do add to MAGI which is used to figure out how much of your Social Security is taxable, and is used for some other tax credits.
And one other option is to sell some investments which have a loss. The losses can be deducted to reduce your taxable income.
I don't know of any simple website or product to figure out all these thresholds and traps. If you do your own taxes with Turbo-Tax or similar, you can what-if some scenarios.
The big trap is IRMAA which burns you for a whole calendar year. Another is your SS being pulled into being taxable income. That one ratchets things up fast.
October 08, 2026, 05:11 PM
PHPaulYes, RMD. A whopping $1400 annually after taxes. Still, that's a couple loan payments...
Be careful when following the masses. Sometimes the M is silent.
October 08, 2026, 05:25 PM
old rugged crossNo, I would not do that. Look for other ways to pay the debt down on the truck. Vehicle payments (loan) suck.
I agree there should be ways for your ira to earn more that 3%.
At your age and income you could take distributions with minimal tax implications and use that money to pay it down/off.
"Practice like you want to play in the game"
October 08, 2026, 05:42 PM
OttoSigIf you have a cash reserve of the same amount why not pay of off with cash, put the payment back in savings every month? You still have the investment in the event of a dire emergency. Or the truck as an asset to sell.
Pay yourself the interest.
Eight years to retirement! Just waiting! October 08, 2026, 05:56 PM
V-TailWhen I was in a similar situation, I just paid more than required. Monthly payments as scheduled, and then, when I sat down each week to pay bills, I would just throw some more at the loan principal. Every little bit helps.
הרחפת שלי מלאה בצלופחים October 08, 2026, 06:12 PM
aibtcCheck out SATA and STRC
October 09, 2026, 10:11 AM
Powers77IMO, doesn't make any sense to withdraw that money to pay off the truck. As others have said you're going to pay more in additional taxes and fees than you are going to save by paying off the loan.
Bigger question is why is it only earning 3% fixed? With a little effort not taking on a huge amount of risk you can do better than that but it needs to be part of your overall financial plan.
October 09, 2026, 10:15 AM
chellim1quote:
Bigger question is why is it only earning 3% fixed? With a little effort not taking on a huge amount of risk you can do better than that but it needs to be part of your overall financial plan.
quote:
The IRA is at 3% because it's CD based and fixed and that was the rate when originated. I am 75 and extremely risk averse.
Inflation is a risk as well.
If you aren't keeping up with inflation, you are losing buying power.
"Some things are apparent. Where government moves in, community retreats, civil society disintegrates and our ability to control our own destiny atrophies. The result is: families under siege; war in the streets; unapologetic expropriation of property; the precipitous decline of the rule of law; the rapid rise of corruption; the loss of civility and the triumph of deceit. The result is a debased, debauched culture which finds moral depravity entertaining and virtue contemptible."
-- Justice Janice Rogers Brown
"The United States government is the largest criminal enterprise on earth."
-rduckwor October 09, 2026, 12:44 PM
229DAKquote:
I would investigate lower interest rate for the truck.
Can you pay extra on the loan's principle (we did that for many years on our home payment)?
Also, would you have a penalty if you pulled money early from the CD?
_________________________________________________________________________
“A man’s treatment of a dog is no indication of the man’s nature, but his treatment of a cat is. It is the crucial test. None but the humane treat a cat well.”
-- Mark Twain, 1902
October 09, 2026, 12:49 PM
6guns^^^ I suspect most loans these days don't have pre-payment penalties. I've done lots of extra principle payments in my time.
SIGforum: For all your needs!
Imagine our influence if every gun owner in America was an NRA member! Click the box>>>

October 11, 2026, 11:14 AM
joel9507quote:
Originally posted by PHPaul:
Does it make sense to withdraw from the IRA to pay off the truck?
The simple answer is no.
The complex answer is also probably no.

Depending on your age, and/or what you would be using the money for, there might not be Federal penalties on removing funds from your IRA. I see you're 75 so the Feds wouldn't penalize withdrawals. That said, if it's a "Traditional IRA" the rules are that you actually have to take out a certain percentage each year (Required Minimum). So, if it's a Trad IRA, it could make sense for you to use the Required Minimum withdrawals to make payments on the truck loan.
That said:
a) there aren't many places to earn tax-free income, but an IRA is one
b) you can't just put money back into an IRA after you take it out, so if you take it out, the tax-free compounding on that money is gone forever
c) if there would be taxes or penalties in your situation, that would compound the reasons to leave the money in the IRA, but you're over the age where penalties would apply
quote:
little income the IRA is providing
That is a different issue and may speak either:
a) to your making different choices within the IRA to earn more, or
b) if options are not available with the institution currently holding your IRA, you could transfer the money tax-free to a different institution (Schwab, Vanguard, etc.) that do offer wide choices and low costs.
quote:
extremely risk averse
As Chellim1 and others suggest, inflation is a risk we all are running, and seemingly-low-risk approaches aren't really low risk, unless they pay better than inflation.
October 11, 2026, 12:58 PM
229DAKquote:
there aren't many places to earn tax-free income, but an IRA is one
A traditional IRA is really tax-deferred, as one pays tax when funds are withdrawn.
quote:
you can't just put money back into an IRA after you take it out
Except in certain, specific situations. Generally, one requires earned income to contribute to a traditional IRA.
_________________________________________________________________________
“A man’s treatment of a dog is no indication of the man’s nature, but his treatment of a cat is. It is the crucial test. None but the humane treat a cat well.”
-- Mark Twain, 1902
October 14, 2026, 08:47 AM
joel9507Saw today's WSJ article on inflation and thought I'd circle back.
Link to unlocked article: WSJ 10/14/26: "Broad Pickup in Prices Lifted Inflation to 3.7% in September" The article has a graph on inflation, the original of which was too big so I resized it:
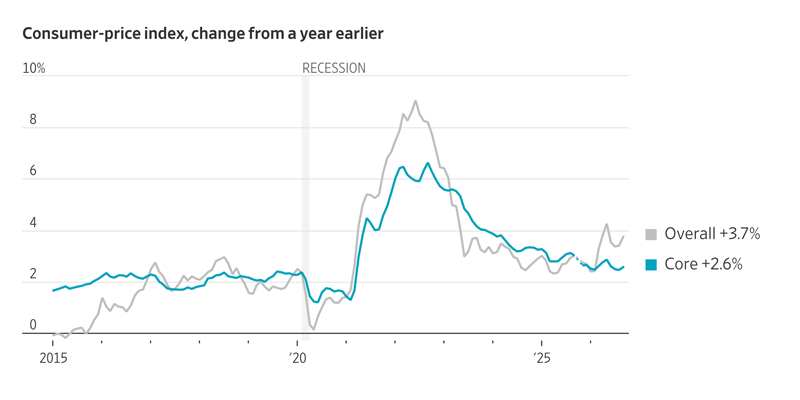
As can be seen, since the pandemic, earning 3% isn't really risk-free once you factor in inflation.
RE: not being able to put money back into an IRA once you've withdrawn it and spent it. That's not to be equated with putting new money into it, which you definitely can (and probably should) do if you qualify.
RE: putting withdrawn money back into an IRA.
link . Once a year you can withdraw from an IRA, keep/use the money for 60 days, and then put the exact full amount back into the source IRA or roll it over to a new IRA. There are special circumstances where the IRS may waive this rule having to do with edge cases (errors, postal delays, service in a war zone, deaths, etc.) but other than that, once it's out for 61 days, it stays out.
October 15, 2026, 08:01 AM
vthokyI'm no financial genius, for sure, but I'm reminded of Mr. Will Gordon, my econ teacher from long ago. Mr. Gordon said, "never prepay on a declining-balance asset."
The example he gave was, coincidentally, a car loan. "You've got money in an account, earning interest. You've got a car that's depreciating. Why would you sacrifice on-hand money plus its potential for earning, to acquire [pay off] something that's worth less every day?"
It made good sense at the time; each person's situation may or may not be applicable to his example.
Politicians seem to have forgotten that they work for us, not the other way around.
— — — — — — — — — — — —
God bless America. October 15, 2026, 09:00 AM
GraniteguyNever pay interest to finance a depreciating asset.
October 16, 2026, 05:34 PM
Snapping TwigThe truck is a DEpreciating asset. Your IRA is an APpreciating asset.
NO!